Homeowners insurance covers a Texas home that receives rain through a damaged roof, potentially covering the cost of roof repairs and the water damage inside the home. According to the Texas Department of Insurance, coverage depends on the cause of the damage and the policy’s conditions. Homeowners policies cover storm damage to roofing materials and rainwater that gets in. Not all roof leaks are eligible for insurance coverage. Insurers identify damage from a covered event from issues involving an old roof, wear and tear, or slow leaks. The roof’s age, condition, and coverage type also affect how the insurer calculates the payment. Homeowners’ out-of-pocket expenses also depend on separate deductibles for wind and hail claims. Understanding these factors helps homeowners see how insurance companies evaluate roof damage and related water damage in a Texas homeowners insurance policy.
When Can Homeowners Insurance Cover a Roof Leak and the Resulting Water Damage?
Home insurance covers a roof leak if a covered event damaged the roof and water entered the home. Covered events include certain storms, wind, hail, or damage from a falling object, depending on the policy. The claim involves roof damage and any resulting damage to interior areas. This includes damaged ceilings, walls, insulation, flooring, and personal items. Not all roof leaks are eligible for coverage. The insurer investigates the cause of the roof damage and assesses whether it resulted from a covered event. Other policy exclusions, limits, and deductibles also influence the final amount. Homeowners must review their policies to see which roof-related losses are covered.
Why Does the Cause of the Roof Leak Matter to the Insurance Claim?
The cause of the roof leak matters in deciding whether the policy covers the damage. Insurers differentiate between damage to the roof (from an event) and water entry (due to old age, deterioration, leaks). A storm-damaged roof is not the same as a roof leaking because of prolonged weather. The Texas Department of Insurance states that homeowners insurance typically does not cover a new roof if the roof is old or worn out. Some insurance policies also do not cover the water damage from slow leaks or seepage. The underwriter reviews the reported events to determine whether a covered event caused the roof damage and water entry. This decision is based on the policy wording and available evidence.
Can the Roof Damage and Interior Water Damage Be Handled Differently in the Same Claim?
Yes, the Roof Damage and Interior Water Damage Can Be Handled Differently in the same claim because different policy provisions apply to each. The insurer can evaluate the two aspects separately within the same claim. The roof component relates to compromised roofing materials and the roofing material coverage provided for repair or replacement. The inner section covers any damage to interior components, including ceilings, walls, insulation, floors, and belongings. A covered storm can cause both types of damage, but payment depends on the policy. The policy has specific settlement guidelines for the roof based on its age, condition, or coverage type. The property’s interior damage is assessed under the property coverage. It doesn’t mean all other elements will be paid automatically if one element of the claim is approved.
How Can Roof Age, Coverage Type, and the Wind/Hail Deductible Affect a Roof Claim Payment?
Roof age and the policy settlement process affect how much the insurance provider pays for roof repair claims. Some insurance policies cover the cost of replacing the water heater, while others reimburse the actual cash value, which considers factors like age and condition. Some insurance providers even use actual cash value pricing for older roofs. The age or condition of an older or worn-out roof can reduce the replacement cost, depending on the policy. Replacement cost policies also provide staged payments, with more money paid out once repairs are underway or if the homeowner submits required documentation. Wind and hail claims have a different deductible than the standard deductible. This is deducted under the policy conditions and affects the homeowner’s out-of-pocket expenses. Reviewing the roof coverage and applicable deductible helps you understand how the insurer calculates payment.
What Evidence Does the Insurer Review in a Roof Leak Water Damage Claim?
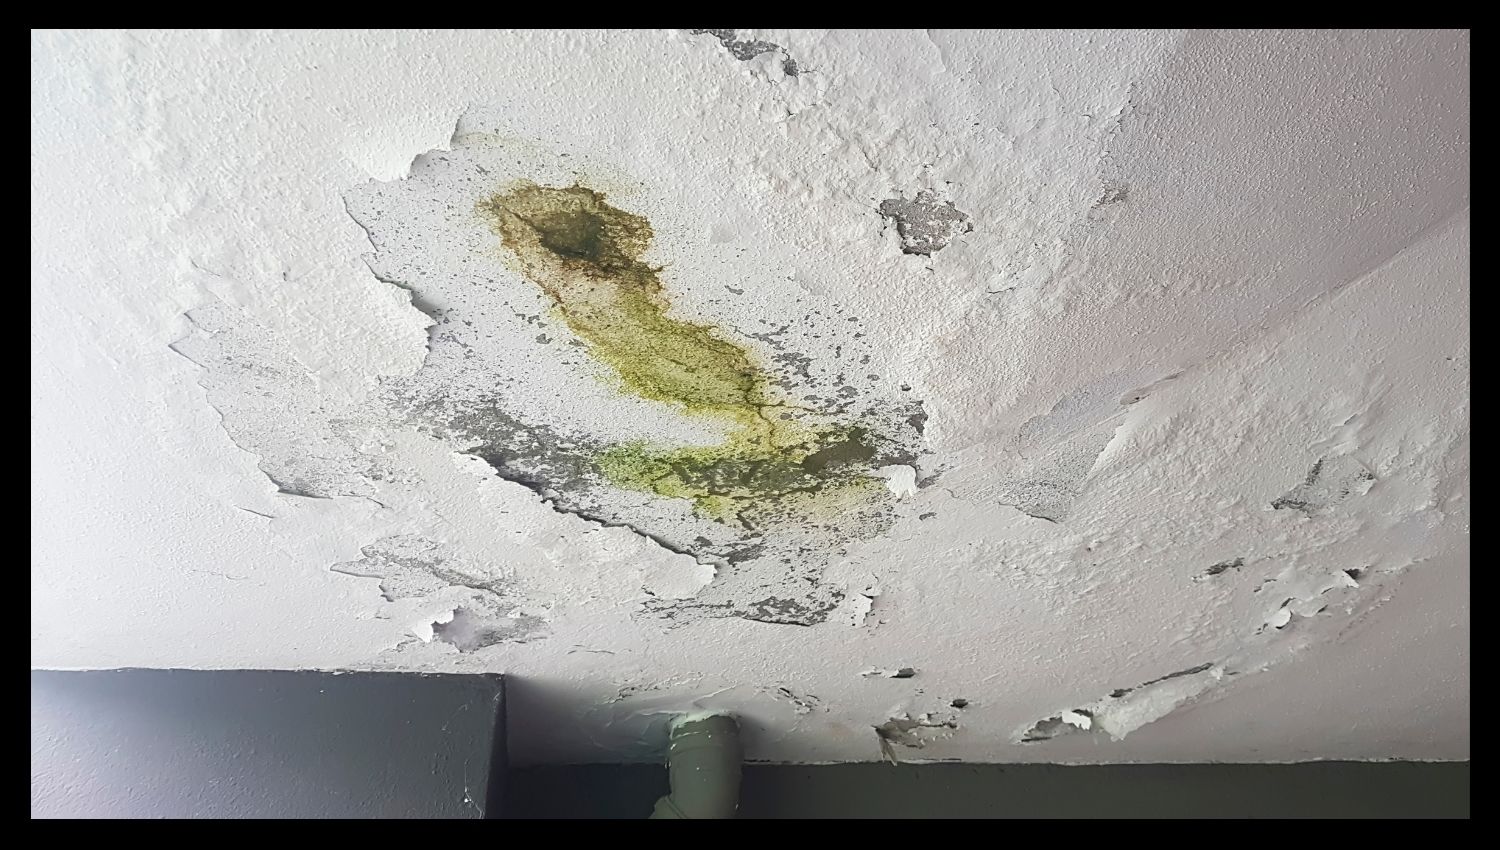
The insurer reviews the evidence to determine what caused the roof damage and whether the interior water damage is connected. Relevant information includes the date of the storm or incident, the roof damage, and where the rain appears to have penetrated the roof area. Photographs or video of the roof and affected interior areas help show the situation before temporary repairs are installed and alter the evidence. Homeowners should photograph roof damage safely; never climb on a damaged roof. A roofer or contractor also uses the data gathered to identify storm damage, impact damage, or failed roofing components. The repair estimate and receipts provide additional information for the reported loss.
How Do Temporary Roof Repairs Affect the Insurance Claim?
Temporary roof repair protects the home from additional water damage while the insurance company investigates the damage. The Texas Department of Insurance considers covering a damaged roof with a tarp a “temporary repair,” and it should be done with reasonable means to protect the damaged property. These steps address short-term exposure but do not replace long-term roof repair. The homeowner should discuss the damage with their home insurance company and allow time for an inspection, if needed, before making permanent repairs. Photographs taken before temporary work help document the original condition and should be taken safely as soon as possible. Property owners are also required to keep receipts for “reasonable temporary repair materials and services. These records provide evidence of measures implemented to safeguard the property and the expenses of temporary measures.